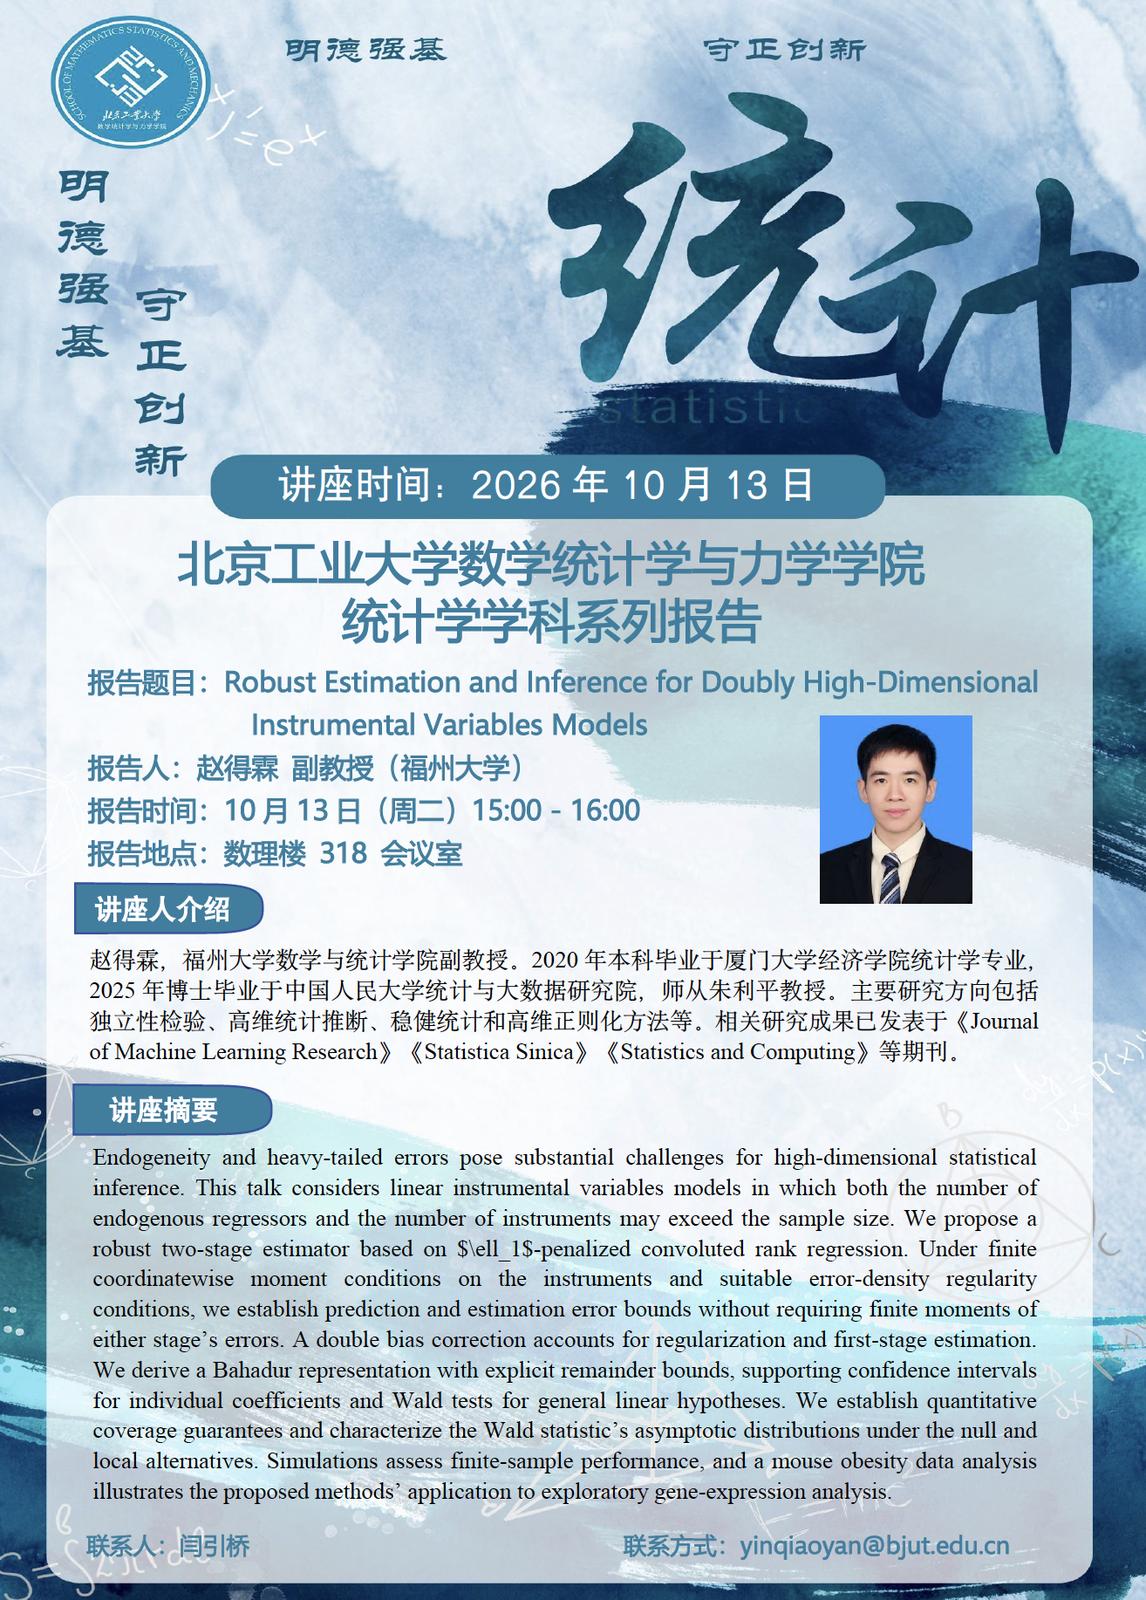
Robust Estimation and Inference for Doubly High-Dimensional Instrumental Variables Models
本次讲座将介绍针对双重高维工具变量模型的稳健估计与推断方法,适用于存在内生性与厚尾误差的高维统计推断问题。
报告介绍
Endogeneity and heavy-tailed errors pose substantial challenges for high-dimensional
statistical inference. This talk considers linear instrumental variables
models in which both the number of endogenous regressors and the number
of instruments may exceed the sample size. A double bias correction accounts
for regularization and first-stage estimation. We derive a Bahaduj representation
with explicit remainder bounds, supporting confidence intervals for individual
coefficients and Wald tests for general linear hypotheses. We establish
quantitative coverage guarantees and characterize the Wald statistic's
asymptotic distributions under the null and local alternatives. Simulations
assess finite-sample performance, and a mouse obesity data analysis illustrates
the proposed methods' application to exploratory gene-expression analysis.
报告人介绍
赵得霖,福州大学数学与统计学院副教授。2020年本科毕业于厦门大学经济学院统计学专业,2025年博士毕业于中国人民大学统计与大数据研究院,师从朱利平教授。主要研究方向包括独立性检验、高维统计推断、稳健统计和高维正则化方法等。
相关研究成果已发表于《Journal of Machine Learning Research》《Statistica Sinica》《Statistics and Computing》等期刊。
报告图片 共 1 张